Insurance Claims
Documenting Wind and Hail Claims: A Blueprint for Approvals
LoadBearing Editorial · · 10 min read
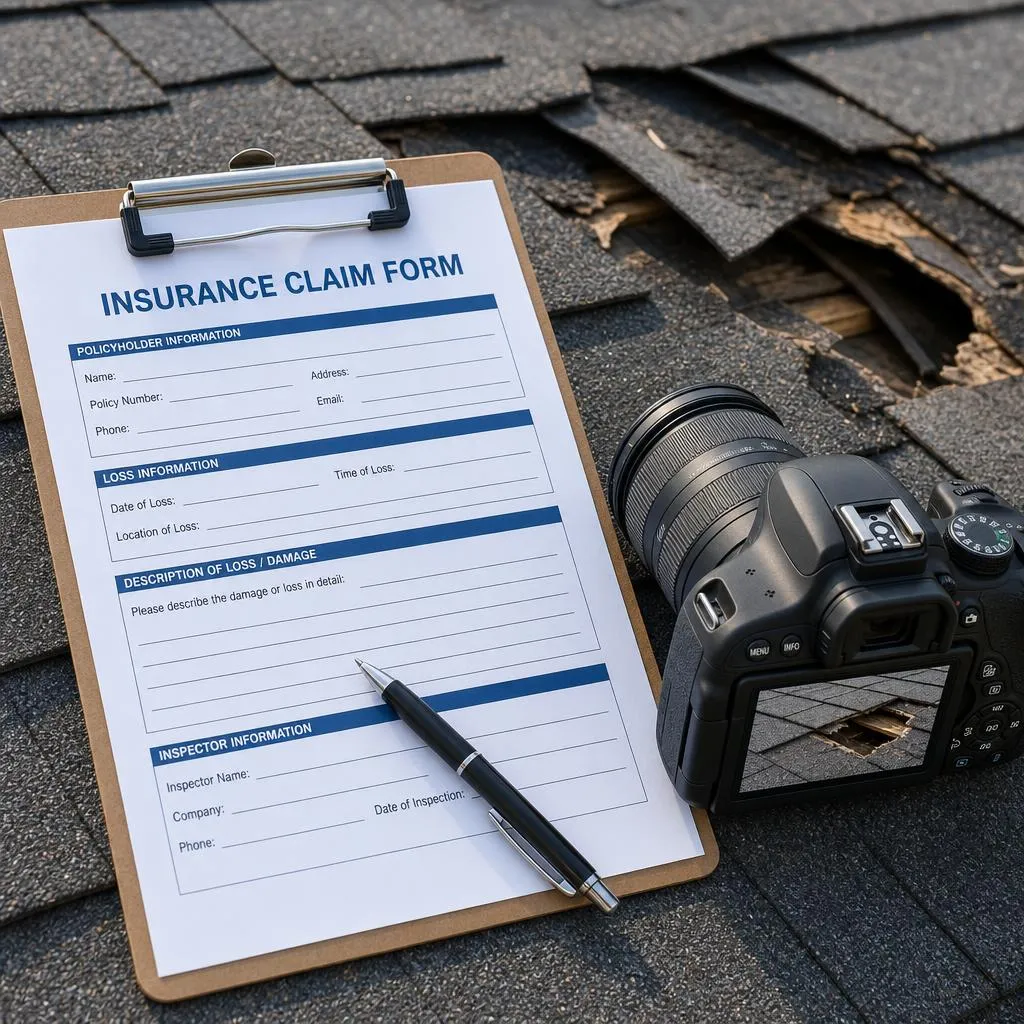
When a massive hail cell sweeps through a residential area, the insurance carriers dispatch catastrophic adjusters by the hundreds. These adjusters are overworked and motivated to close files quickly. If a contractor submits a poorly documented claim, it will be delayed, underpaid, or denied outright.
What photos does a hail damage claim need?
A hail claim needs photos of all four elevations, a roof overview, marked test squares on each slope, collateral damage to soft metals, and any interior leaks.
A successful insurance claim is won during the first inspection. You are not just looking for damage; you are building a legal case.
Using LoadBearing CRM on a mobile device, field representatives must systematically photograph the property. The standard protocol requires photos of all four elevations, the roof overview, specific test squares (e.g., 10x10 grids showing hail hits), collateral damage (gutters, downspouts, window screens, HVAC fins), and interior leaks. Because the CRM allows unlimited photo uploads directly to the client's file, there is no excuse for missing a critical shot.
When should the contingency agreement be signed?
Sign the contingency agreement after the inspection and before you invest time meeting adjusters or writing a full scope.
Before investing hours into meeting with adjusters and writing scopes, the contractor must secure a signed Contingency Agreement. This document ensures that if the claim is approved, your company is guaranteed the work.
Paper contingency agreements get lost or delayed. With LoadBearing's Pro Docs feature, the sales rep can pull up the standard legal template, fill in the homeowner's details, and capture a digital signature immediately upon descending the ladder. The document is stored permanently and can be emailed to the homeowner automatically.
Presenting the Scope to the Adjuster
When writing the estimate, clarity is your best weapon. Grouping items logically (e.g., Roof, Elevation 1, Elevation 2, Interior) mirrors the software used by most insurance carriers.
LoadBearing CRM’s estimating templates allow you to build out highly detailed, itemized scopes of work that leave no room for interpretation. By attaching the chronological photo reports to the detailed estimate, you hand the adjuster a complete, defensible package. They don't have to guess why you are requesting 40 linear feet of ridge vent; the photos prove it is damaged, and the estimate prices it accurately.
Managing Homeowner Anxiety
The insurance process can take weeks. Homeowners get anxious and will call your office daily for updates. By utilizing LoadBearing’s Client Portal and automated SMS features, you can proactively notify the client when the adjuster meeting is scheduled, when the initial scope is submitted, and when production is ready to begin. Transparent communication keeps the client calm and keeps your phone lines clear for new sales.
A sample photo checklist for one roof
The list below is an example structure, not a carrier requirement. Adjust it to the carriers and roof types you see most often.
- Front, rear, left and right elevations, each from far enough back to show the whole wall.
- One overview per roof slope, then a marked test square on each slope with a close-up of every counted hit.
- Soft metals: gutters, downspouts, vents, flashing and HVAC fins, with a chalk circle around dents.
- Window screens, siding and fences on the storm-facing side.
- Interior ceiling stains or leaks, with a wider shot showing which room they are in.
- Date-stamped context, such as a shot of the street address, so the photo set clearly belongs to this property.
How do you tell hail damage from wear?
Hail damage usually shows as random impacts with granule loss and a soft or fractured mat underneath, while wear tends to be uniform across a slope or concentrated where water flows. Blistering, foot traffic scuffs and manufacturing defects can look similar in a photo, so take a close-up and a wider shot of each mark to show the pattern, not just the spot. If you are unsure, say so in your notes rather than overstating the cause; an adjuster who catches one exaggerated photo will question the rest.
Limits and edge cases
- Prior damage. If the roof had a previous claim or repair, document what is old and what is new. Mixing them weakens the whole file.
- Matching. Whether a carrier pays for matching materials depends on the policy and local rules. Do not promise a homeowner full replacement because a discontinued shingle cannot be matched.
- Wind-only damage. Lifted or creased shingles may not show impacts at all. Photograph the crease line and the missing seal strip, and note the storm date.
- Unsafe roofs. If a slope is too steep or damaged to walk safely, do not. Use measurements and imagery instead, and note that the slope was not walked.
The goal of the file is that an adjuster who never visits the property can still see what you saw. Every photo should answer a question the scope raises.
How long does a well-documented claim take?
There is no fixed timeline, because it depends on the carrier, the storm volume and the adjuster's caseload. What documentation changes is the number of round trips. A complete first submission avoids the cycle of request, re-inspection and resubmission that adds weeks. Keep homeowners informed with each milestone so silence is not mistaken for inaction.
Filed under Insurance Claims, Storm and Roofing
Related field notes
- Surviving Storm Work: Cash Flow and CRM Features for Roofers · Roofing
- Precision Bidding with EagleView and LoadBearing CRM · EagleView
- Mastering Insurance Claims: From Fire Damage to Final Payout · Fire Damage Claims
Ready to stop letting jobs fall through the cracks? Start a 14-day free trial.